Elite Crest One Properties Elite Crest One Properties

About Us


About
Elite Crest One


At Elite Crest One, we believe that exceptional spaces create extraordinary lives.

We curate and present the finest real estate opportunities across Dubai, connecting discerning buyers with properties defined by prime locations, timeless design and enduring value.

Our commitment is simple — to deliver excellence in every detail and build lasting relationships based on trust, transparency and results.


Exceptional spaces.
Lasting addresses.

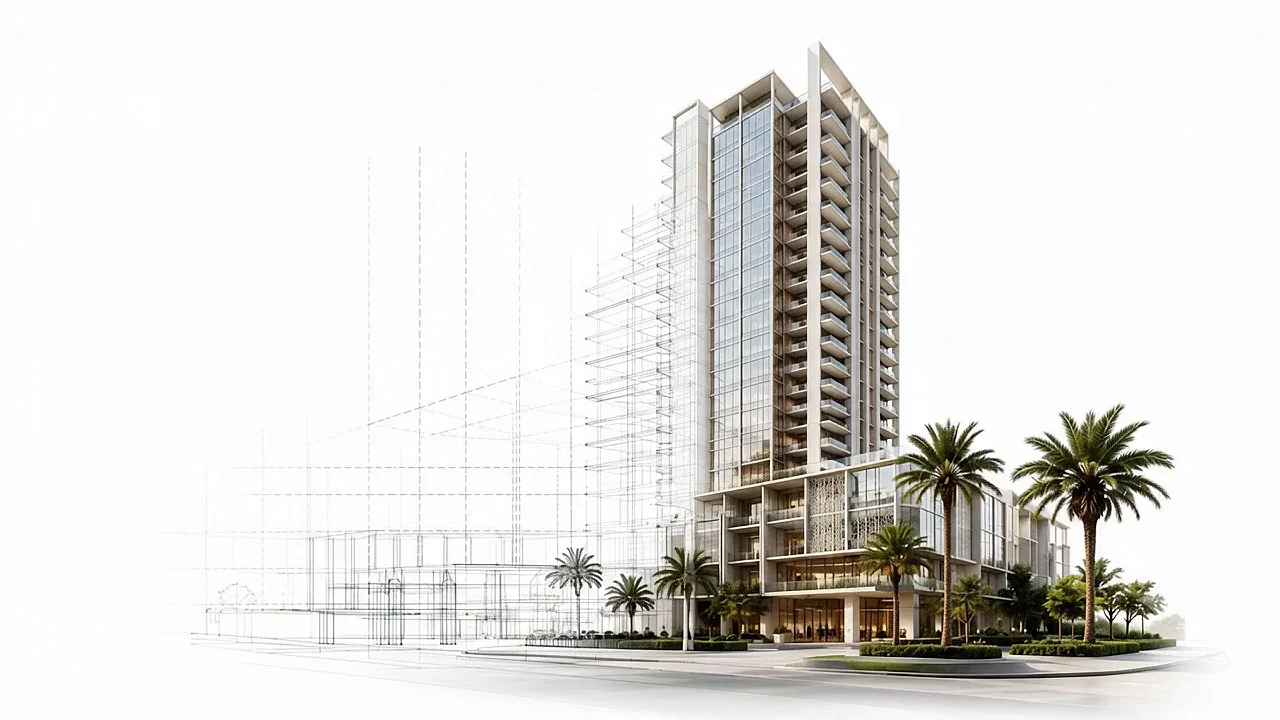
Elite Crest One residential tower, architectural visualisation

How we work


Four things you can
hold us to

01

One person, start to finish

The consultant who takes your first call is the one who shows you the unit, negotiates the terms, sits with you at the transfer and picks up the phone a year later. No handover to a call centre, no re-explaining yourself to someone new.

02

Priced on evidence, not on asking prices

Every figure we give you is checked against registered Dubai Land Department transactions and the developer's current release, not against what other agents are hoping to get. If we cannot support a number with a document, we will not quote it.

03

We will tell you no

Some projects do not hold up — on the developer's delivery record, on the payment plan, or on what the unit is likely to be worth at handover. When that is the case we say so, show you why, and find you something that does. Our reputation is worth more than one deal.

04

Here after the keys

The transfer is where most brokers stop. It is where we carry on: snagging, handover, furnishing, tenanting, management and, when the time is right, resale. One relationship across the whole life of the asset, which is the only way to see it properly.

What we stand for


Three words on
the door

They are on our logo, and they are the test every piece of advice has to pass before it reaches you.

Building trust

Every fee is written down before you commit. Every claim we make about a project is backed by a document you can read. Every consultant is RERA-registered and named on the work they do. Trust is not something we ask for — it is what is left when nothing has been hidden.

Creating value

Owning property in Dubai is easy. Buying well is not. Value comes from the entry price, the way the payments are structured, the yield the unit will actually produce and the exit it will eventually have — and we think about all four before we put anything in front of you.

Elevating lifestyles

An asset is only ever a means. What it is for is a home that improves how you live, or an income that improves what you can do with your time. We keep that in view, because a purchase that performs on paper but not in life has not done its job.

Visit us


Our office
in Arjan

Office

412B, Diamond Business Center
Block B, Arjan
Dubai, United Arab Emirates

Visits are by appointment, so that the consultant who knows the area you are interested in is the one in the room. Call ahead or send an enquiry and we will set a time.

Questions


Buying and investing
in Dubai

Why do people buy property in Dubai?

Three reasons come up in almost every conversation we have. There is no annual property tax and no personal income tax on rent, so what a property earns is largely what you keep. Rental yields are high by the standards of most major cities. And since 2002 foreigners have been able to own freehold property outright in designated areas, with the title registered in their own name at the Dubai Land Department.

Behind those sits a city that keeps growing — in population, in infrastructure and in the number of people who want to live here — which is ultimately what supports both rents and prices over time. None of that makes every purchase a good one. It makes Dubai a market worth understanding properly before you commit.

What is the difference between freehold and leasehold?

Freehold means you own the property and its share of the land outright, for as long as you like, and can sell it, rent it out or pass it on without restriction. It is only available in areas the government has designated for foreign ownership, but those areas now cover most of the places international buyers actually want to live.

Leasehold gives you the right to occupy and use a property for a fixed term, usually up to 99 years, after which it reverts to the freeholder. It is less common in the areas we work in and generally trades at a discount to freehold for that reason. Almost everything on this site is freehold; we will always say so if something is not.

How does buying off-plan actually work?

You reserve a unit from the developer before or during construction, pay a deposit, and then pay the balance in instalments tied to construction milestones or a fixed schedule. Some plans run entirely up to handover; others carry a portion beyond it, so you are paying part of the price after you already hold the keys.

Your money does not go into the developer's general account. Dubai requires each project to have its own escrow account, regulated by RERA, from which funds are released only as construction is certified. Your purchase is registered on the land department's Oqood system, which gives you a recognised interest in the unit before the title deed exists. The appeal is entry pricing and a spread-out payment; the trade-off is that you are buying a building that is not yet built, which is exactly why the developer's track record matters more than the brochure.

What fees should I budget for on top of the price?

The one everyone knows is the Dubai Land Department transfer fee, which is 4% of the purchase price and is paid on registration whether you buy off-plan or ready. Add a small fixed registration and trustee fee on top of that.

Beyond the government fees, expect an agency commission (2% is the market norm on ready property; on off-plan the developer usually pays it), a NOC fee from the developer if you are buying a resale in their building, and, if you are financing, the bank's valuation and arrangement fees plus mortgage registration at 0.25% of the loan. Once you own it, the running cost is the annual service charge, set per square foot by the building. We put all of this in writing for any specific unit before you commit to it.

Can I get a mortgage if I do not live in the UAE?

Yes. Several UAE banks lend to non-residents on completed property, and a few will lend on off-plan from selected developers. The loan-to-value is lower than a resident would get — typically 50 to 60% of the valuation, so you should plan on a larger deposit — and banks will want to see income documents from your home country.

Rates, terms and the list of banks that will lend to a given nationality change often enough that we do not publish them here. Tell us what you are looking at and we will check current availability rather than quote a figure that is out of date.

What rental yield can I expect, and who deals with the tenant?

Gross yields in Dubai commonly sit between 5 and 8% of the purchase price depending on the area and the type of unit, with smaller apartments in established communities usually at the higher end and villas at the lower. Net yield, after service charges and any management fee, is what actually matters and is what we quote.

If you are not in the country, someone needs to find and vet the tenant, register the contract, collect rent, handle maintenance and manage the renewal — and rent increases in Dubai are governed by a published index, not set freely. That is the service our rental team provides, so the property earns without you having to be here.

Does buying property give me a residence visa?

It can. Property investment is one of the routes to the UAE's long-term residence visa. At the time of writing, real estate worth at least AED 2 million qualifies the owner for a ten-year Golden Visa, and that figure can be met across more than one property. Mortgaged and off-plan purchases can qualify under certain conditions.

The rules are set by the government and have been adjusted several times, so treat this as a starting point rather than a promise. If residency is part of your reason for buying, tell us at the outset and we will structure the purchase with that in mind and confirm the current requirements before you commit.

Fees, lending terms and visa thresholds change. Everything above is indicative — we confirm the current rules for your situation before you commit.